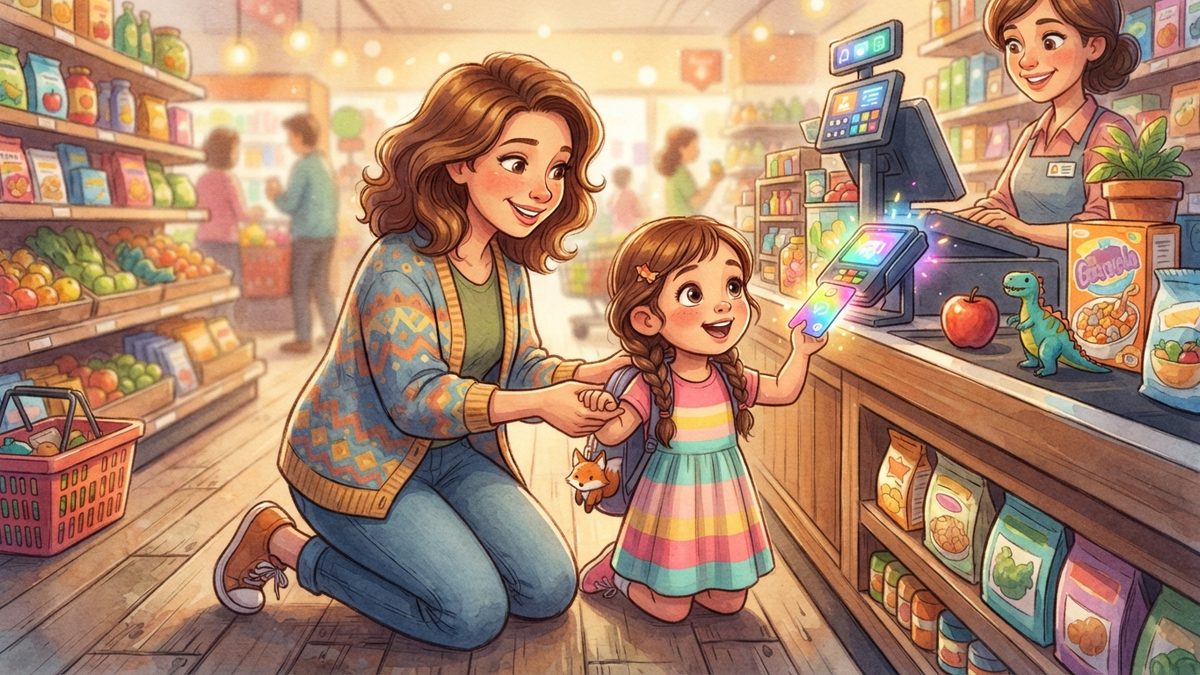
To a four-year-old standing in the supermarket checkout line, a smartphone or plastic card looks like an enchanted wand. You tap the glowing screen against a black box, a cheerful chime sounds, and the cashier hands over a bag of groceries or a brand-new toy.
When it comes to explaining credit cards to kids, today's parents face a developmental challenge unique to the cashless era. Without physical coins or bills changing hands, digital-native children naturally assume that payment cards possess unlimited, free purchasing power.
Demystifying "invisible money" is essential for building emotional resilience, self-regulation, and healthy boundary comprehension in early childhood.
Age by which lifelong core money habits and delayed gratification pathways are formed
vs. age 12+ when standard formal financial literacy education typically begins in schools
The Cognitive Illusion of the "Magic Plastic Card" #
Young children are concrete thinkers. According to cognitive development frameworks pioneered by Jean Piaget and supported by the Harvard Center on the Developing Child, children under age seven perceive the world strictly through tangible, sensory experiences.
When cash was the primary medium of exchange, the trade-off of purchasing was unmistakable. A child saw three paper dollar bills leave their parent's hand and enter a register; once those physical bills were gone, the wallet was visibly empty.
Tap-to-pay interfaces, digital wallets, and credit cards erase that tactile feedback loop. The card always returns directly to your pocket, creating the illusion of infinite supply without labor, scarcity, or trade-offs.
When children do not understand that digital cards represent finite hours of real-world effort, store limits feel arbitrary and unfair. Helping children understand digital currency is closely tied to how to teach kids wants vs needs, transforming checkout confusion into calm cooperation.
Why Explaining Credit Cards to Kids Demands "Sturdy Warmth" #
When a child demands an impulse purchase and insists you "just tap your phone," parents often swing between two unhelpful extremes: permissive surrender or punitive frustration.
A balanced, sturdy parenting approach integrates high emotional warmth with clear, non-negotiable boundaries. We validate our child's excitement about the item while maintaining calm authority over the family financial boundary.
| Parenting Style | Response to "Just Tap Your Card!" | Underlying Message to Child | Long-Term Developmental Outcome |
|---|---|---|---|
| Permissive (Low boundaries, high softness) | "Okay, just this once, but don't ask again!" | "Whining bypasses financial limits." | Impulsive spending, low frustration tolerance, entitlement. |
| Authoritarian (High rigidity, low warmth) | "Stop asking! Money doesn't grow on trees! You're ungrateful." | "My desires are bad; money creates relational tension." | Financial anxiety, covert spending, emotional dysregulation. |
| Sturdy / Authoritative (High warmth, firm limits) | "You really love that truck. AND we are not buying toys today. Our card money is reserved for dinner ingredients." | "My feelings are safe, but adult boundaries are stable and secure." | Emotional regulation, delayed gratification, clear fiscal reality. |
"When a child is emotionally dysregulated, connection must precede correction. First provide physical presence and emotional attunement, then firmly hold the boundary. A child does not need us to solve their disappointment—they need us to remain sturdy while they feel it."
— Dr. Daniel Siegel & Dr. Tina Payne Bryson, Authors of The Whole-Brain Child
The Metaphor That Works: The "Invisible Bucket" #
Abstract balance sheets confuse developing brains, but concrete visual metaphors bridge the cognitive gap immediately.
Explain that a credit card or digital wallet is simply an invisible pipeline connected to a family bucket of water at home:
- The Work Pump: Going to work pumps a specific amount of water into the family bucket.
- The Card Pipeline: The plastic card is a hose. Every time you tap the card, a scoop of water pours out of the bucket to pay the store.
- The Finite Limit: If you tap the card too many times for treats, the bucket runs dry, leaving no water for essentials like electricity, warm water, or food.
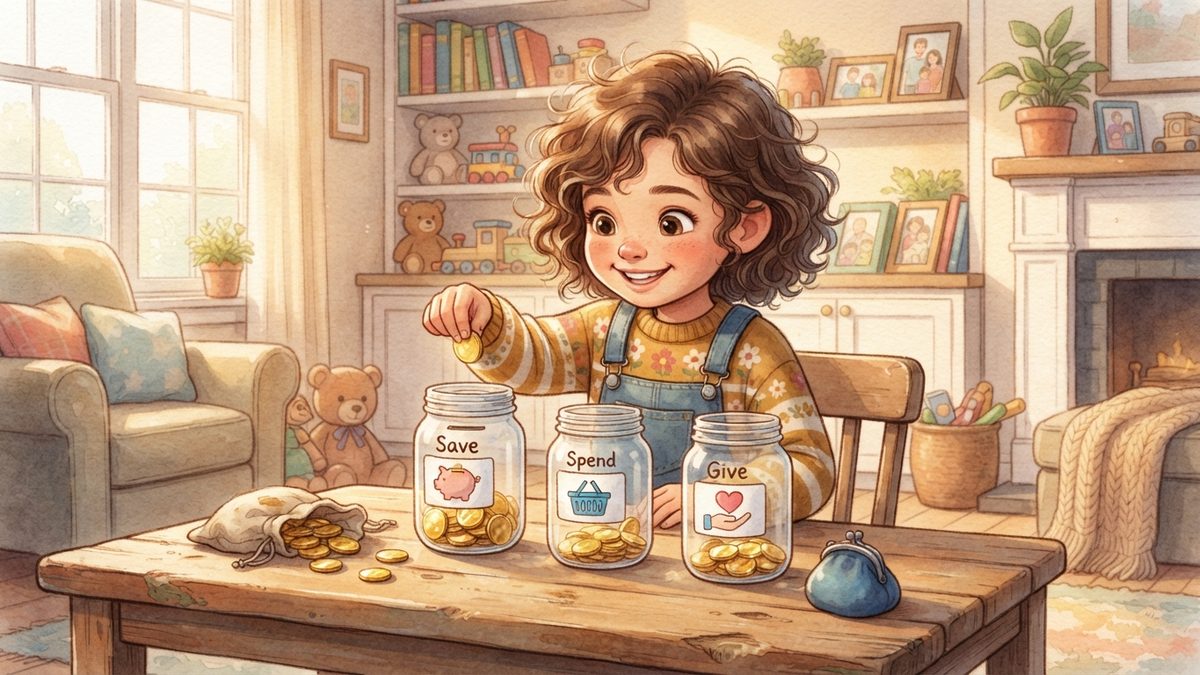
This metaphor honors the child's intelligence by grounding abstract banking mechanics in a physical reality they can visualize. Pairing this mental model with concrete tools like the 3-jar allowance system for kids gives young children direct, hands-on mastery over their own tangible resources.
Step-by-Step Routine: Demystifying Digital Money at Home #
To eliminate store tantrums before they begin, implement this predictable 4-step sequence tonight at home.
Step 1: The Concrete Bucket Demonstration (Tonight at 7:30 PM) #
Sit down with your child and a clear glass pitcher filled with water alongside three smaller empty cups labeled "Home & Food," "Fun & Treats," and "Future Dreams."
Pour water from the main pitcher into the cups. Demonstrate that pouring too much into "Fun & Treats" empties the main reservoir. Hand them your payment card and explain: "This card is just a straw that drinks from our pitcher."
Step 2: The Pre-Store "Mission Briefing" #
Before walking into any retail environment, set the perimeter before touching the cart:
"Today our card is only buying the items on our grocery checklist. We are not buying toys or surprise treats today. If you see something you love, we will take a photo of it for your Wish List."
Step 3: The Collaborative Checkout Scan #
Involve your child actively in the transaction instead of keeping them a passive observer. Let them hold the paper receipt.
Show them the printed numbers: "See this number? That tells our bank to send exact water drops from our bucket to this store."
Step 4: Sturdy De-escalation If Resistance Occurs #
If your child has a meltdown over a declined impulse purchase, do not lecture or negotiate. Stay physically close, lower your vocal pitch, and acknowledge their distress without budging:
"I hear how much you wanted those stickers. It feels hard to walk away without them. I am holding you through this disappointment, and the answer is still no."
Exact Word-for-Word Scripts for Real-World Scenarios #
Keep these scripts ready when invisible money triggers friction in public:
Scenario 1: "Just tap your phone! It's so easy!" #
- Parent: "The phone makes it look like magic, doesn't it? But every tap takes real hours of work out of our family bank. Today, our taps are only for dinner groceries."
Scenario 2: "You have your card, that means you have money!" #
- Parent: "The card is just a key to a locked box. The box only has a set amount of coins inside. If we use those coins on this toy, we won't have enough coins left for our weekend trip."
Scenario 3: Whining or bargaining at the register #
- Parent: "I see how much you love that item. You wish we could bring it home right now. AND our plan for today is set. Let's snap a photo for your birthday list."
Using Interactive Stories to Solidify Invisible Concepts #
Developmental neurobiology demonstrates that children process complex moral and social constructs best through narrative transportation. When characters in stories encounter trade-offs, earn rewards through effort, and manage big feelings around delayed gratification, young listeners mirror those neural circuits without experiencing real-world stress.
Fabella harnesses the power of interactive audio and visual storytelling to make abstract concepts instantly relatable.
Through voice-narrated adventures, Fabella places children inside engaging stories where characters navigate real choices—saving resources, distinguishing between needs and wants, and understanding how community work transforms into shared rewards.
By engaging both auditory and visual pathways through rich, dual-coded narratives, Fabella transforms financial abstractions into grounded, lifelong emotional intelligence.
[!TIP] Recommended Deep-Dive: If you are exploring this topic, read our clinical guide on Teaching Kids Delayed Gratification with Money for proven scripts and routines.
Action Plan for Parents #
- Ditch the "magic card" silence: Talk aloud during checkout transactions: "I'm tapping my card to transfer $12 from our work account to buy these apples."
- Implement the Wish List Photo method: Validate their taste by documenting desired items rather than buying or arguing.
- Anchor abstract money in tangible stories: Use structured metaphors and daily narrative storytelling to instill patient, confident financial habits early.